
Why Filing Status Matters
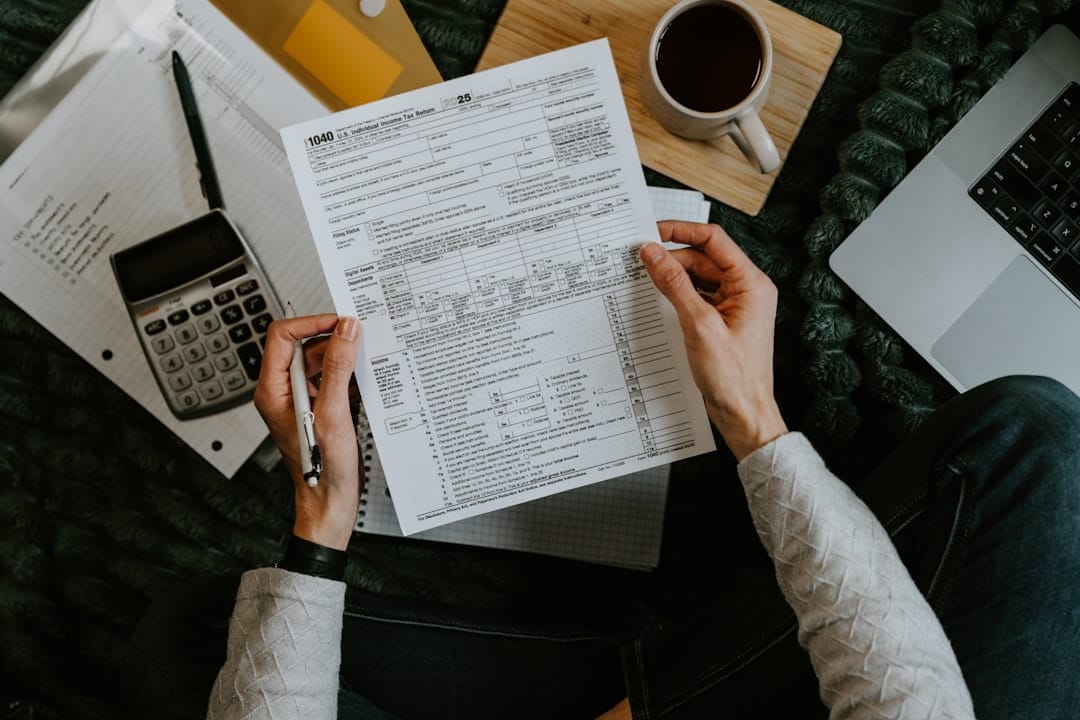
Photo by Kelly Sikkema on Unsplash
Filing status is one of the first things you determine when preparing a federal tax return, and it affects nearly every calculation that follows. Your status determines your tax bracket thresholds, the size of your standard deduction, and your eligibility for many credits and deductions. Choosing the wrong status — or failing to understand which status applies — can mean paying more tax than you owe or claiming benefits you do not qualify for.
The five federal filing statuses are: Single, Married Filing Jointly (MFJ), Married Filing Separately (MFS), Head of Household, and Qualifying Surviving Spouse. Your marital and household status on December 31 of the tax year determines your filing status for that entire year. If you marry on December 31, you are considered married for the full year. If your spouse dies during the year, special rules determine which status is available to you.
Understanding the distinctions between statuses is not just an academic exercise. The difference between filing as Single versus Head of Household, or between MFJ and MFS, can change your standard deduction by thousands of dollars and shift where your income falls within the bracket structure — affecting your actual tax bill in meaningful ways.
Married Filing Jointly vs. Separately
Photo by Vitaly Gariev on Unsplash
Most married couples file jointly because MFJ provides the most favorable bracket thresholds, the highest standard deduction ($29,200 in 2024), and access to credits that are unavailable or heavily restricted for MFS filers. However, MFJ can produce what is often called a "marriage penalty" for couples where both spouses earn similar high incomes. The MFJ bracket thresholds for the upper brackets are less than double the corresponding Single thresholds, meaning two high earners combined may pay more tax as a married couple than they would have as two single individuals.
Married Filing Separately eliminates joint and several liability — the legal exposure each spouse has for the other's tax errors or underreporting. But filing separately forfeits the EITC, education credits, and the ability to contribute to a Roth IRA if income is above a very low threshold. The MFS standard deduction also equals the Single amount, not the MFJ amount, and bracket thresholds are compressed. For the vast majority of couples, MFS produces a higher combined tax bill.
The primary legitimate reason to file MFS is income-driven repayment (IDR) of federal student loans. IDR plans calculate monthly payments based on the borrower's individual income when they file separately, rather than household income when filing jointly. For a borrower with substantial student debt and a high-earning spouse, the payment reduction from filing separately can exceed the additional tax cost — making MFS the better financial choice despite its tax disadvantages.
Head of Household
Photo by Vitaly Gariev on Unsplash
Head of Household (HOH) is available to unmarried taxpayers who paid more than half the cost of maintaining a home for a qualifying person for more than half the year. A qualifying person is typically a child you can claim as a dependent, but it can also be a dependent parent — even if the parent does not live with you, provided you paid more than half the cost of their home. You cannot claim HOH if you are married, with limited exceptions for spouses who lived apart for the entire second half of the year and meet additional conditions.
HOH provides a standard deduction of $21,900 in 2024, compared to $14,600 for Single, and it has more favorable bracket thresholds than the Single status. This difference is specifically designed to recognize the additional financial burden on single parents and those supporting dependents alone. A single parent with one child who qualifies for HOH will pay meaningfully less tax than a single person with no dependents earning the same income.
Incorrectly claiming Head of Household is one of the more commonly audited filing positions, particularly for lower-income filers. Common errors include claiming HOH while technically still married (or before a divorce is legally finalized), or failing to meet the "more than half the year" requirement for the qualifying person's presence in the home. The IRS screens HOH claims carefully because the status provides a significant tax benefit and the eligibility rules are frequently misunderstood.
Qualifying Surviving Spouse and Dependent Status
Photo by Zulfugar Karimov on Unsplash
A taxpayer whose spouse died in either of the two prior tax years — and who has a qualifying dependent child — may file as a Qualifying Surviving Spouse. This status allows the use of MFJ bracket thresholds and the MFJ standard deduction, providing the same favorable tax treatment as if the taxpayer were still married. It is available for two years following the year of the spouse's death. After those two years, the taxpayer typically transitions to Head of Household if a qualifying child remains in the home, and then to Single after the child no longer qualifies.
The dependency rules — determining who counts as a dependent on whose return — carry significant downstream consequences. A dependent child can support eligibility for the Child Tax Credit, the EITC, the Child and Dependent Care Credit, and the ability to claim HOH status. These benefits can be worth thousands of dollars annually, and the rules for who qualifies as a dependent are detailed: the child must meet age, relationship, residency, and support tests.
Only one taxpayer can claim any given individual as a dependent in a single tax year. When parents are divorced or separated, this creates a common point of conflict. The IRS has tiebreaker rules that generally favor the parent with whom the child lived for more days during the year. Parents can also agree to alternate claiming the child in different years using a specific IRS form, but only one may claim the dependency exemption and related credits for any given year. Attempting to claim the same child twice — whether accidentally or intentionally — triggers automatic IRS scrutiny and typically results in rejection of one of the returns.