
Sizing a Speculative Position
Photo by Campaign Creators on Unsplash
Portfolio allocation to cryptocurrency requires confronting its fundamental characteristics honestly: extraordinary volatility, unproven long-term value storage, uncertain regulatory environment, and potential for total loss — alongside genuine potential for very large returns if the technology and monetary thesis plays out over decades.
Standard portfolio theory frameworks, developed for normally distributed returns and stable correlations, apply imperfectly to an asset that can halve three times in two years or multiply tenfold in one year. A different analytical lens is needed.
The Kelly Criterion and Asymmetric Bets
Photo by Sasun Bughdaryan on Unsplash
The Kelly Criterion, developed by John Kelly at Bell Labs in 1956, provides a mathematical framework for sizing bets where the return distribution is known. For a bet where you know the probability of success and the payoff, Kelly suggests the fraction of capital to wager that maximises long-run growth.
Applying Kelly to Bitcoin requires estimating: the probability of very large gains (technology adoption thesis succeeds), the probability of substantial or total loss (technology fails, regulation bans, better alternative emerges), and the magnitude of each outcome. These inputs are deeply uncertain — any "Kelly-optimal" calculation for Bitcoin is built on speculative assumptions.
The practical conclusion from Kelly-style thinking: given Bitcoin's extreme variance and significant probability of failure, the mathematically optimal allocation is small — typically single-digit percentage of a diversified portfolio. Even if you believe the bull case is likely, the variance penalty (volatility drag) from holding a large position in a highly volatile asset argues for concentration limits.
Common Allocation Frameworks
Photo by Niko Nieminen on Unsplash
The 1–5% rule: many institutional investors and advisers suggest that crypto should constitute no more than 1–5% of a diversified portfolio. At 1%, even a total loss is portfolio-survivable. At 5%, a total loss is painful but not catastrophic. This sizing preserves the asymmetric upside without catastrophic downside risk.
Sharpe-ratio analysis: Bitcoin's Sharpe ratio (risk-adjusted return) has historically been impressive on a long-term look-back, largely because returns have been extraordinary. However, the Sharpe ratio doesn't capture fat-tail downside risk (drawdowns of 80%+) well. Adding a maximum-drawdown constraint typically limits crypto allocation more severely than Sharpe alone.
Your specific circumstances: risk tolerance, investment horizon, tax situation, and financial need for the capital all matter. Someone with a 30-year horizon who will not need the capital can tolerate greater volatility than someone with a 5-year horizon saving for a house deposit. Crypto is never appropriate as a repository for capital needed in the near term.
When Not to Invest
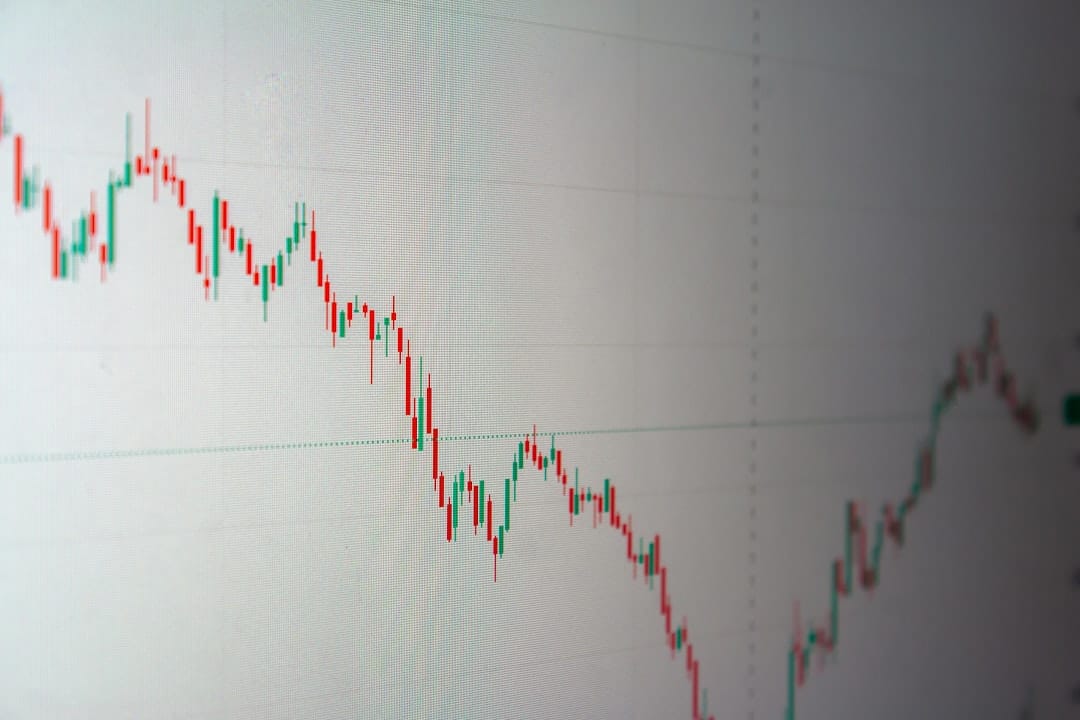
Photo by Arturo Añez on Unsplash
Borrowed money: leverage on an already highly volatile asset creates the risk of ruin — total capital loss plus ongoing debt obligations.
Emergency fund capital: money needed for short-term obligations or unexpected expenses should never be in crypto.
Capital you cannot afford to lose: the standard investment disclaimer is particularly important here — there is a non-trivial probability of permanent capital impairment in any individual crypto asset.