
The Core Principle
Photo by Jakub Żerdzicki on Unsplash
At the heart of all serious equity valuation is a single idea: a company is worth the present value of all the free cash flows it will ever generate. This principle was formalised by John Burr Williams in The Theory of Investment Value (1938), one of the most important books in the history of finance. Williams argued that the intrinsic value of any financial asset — bond, share, or real estate — could be derived mathematically from its future income stream, discounted to the present day.
The intuition is straightforward. A pound received ten years from now is worth less than a pound received today — because you could invest today's pound and have more than a pound in ten years. The further into the future a cash flow lies, and the less certain you are of receiving it, the less it is worth today.
The DCF Formula
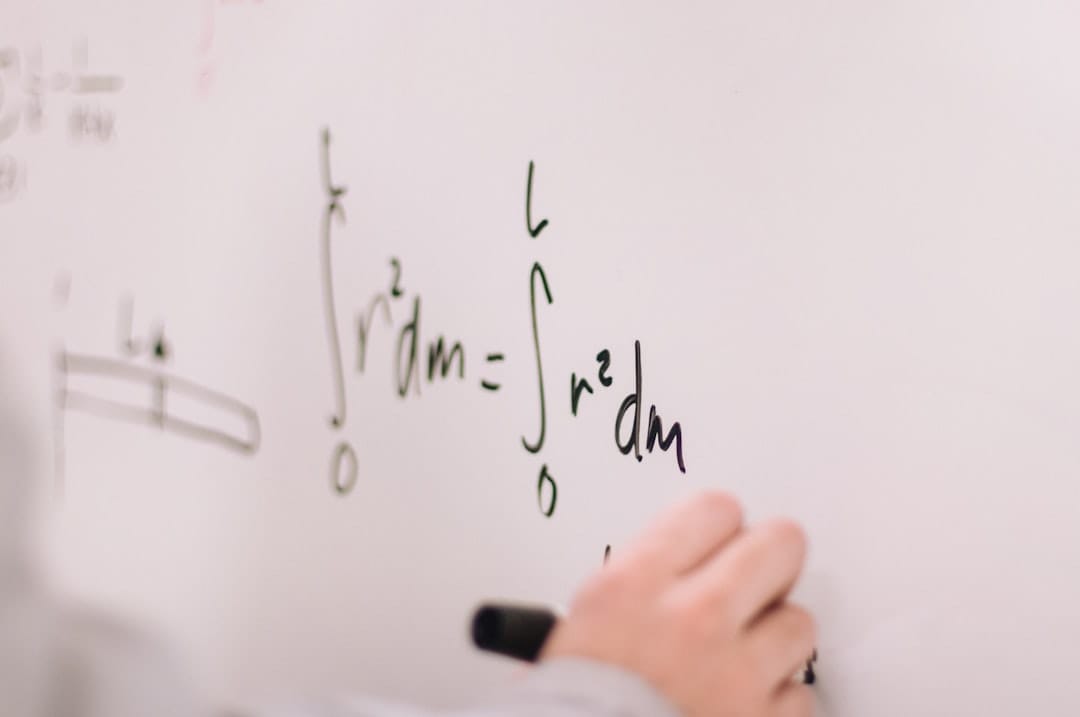
Photo by Jeswin Thomas on Unsplash
In its simplest form, Discounted Cash Flow (DCF) valuation estimates:
Value = FCF₁/(1+r) + FCF₂/(1+r)² + FCF₃/(1+r)³ + … + Terminal Value/(1+r)ⁿ
Where FCF is the free cash flow in each year and r is the discount rate — the required rate of return that reflects both the time value of money and the riskiness of the business.
Free cash flow is not the same as accounting profit. It is the cash a business generates after paying for the capital expenditures needed to maintain and grow operations — cash that is genuinely available to be returned to shareholders or reinvested elsewhere.
Terminal Value
Photo by Fabio Fistarol on Unsplash
A DCF cannot project cash flows to infinity year by year. Instead, analysts typically project explicit cash flows for five to ten years, then add a terminal value: an estimate of the company's value at the end of the projection period, usually calculated using a perpetuity formula. In most DCF analyses, the terminal value accounts for 60–80% of the total estimated value. This is simultaneously the most important and the most uncertain part of the exercise — small changes to the assumed long-run growth rate or discount rate in the terminal value can swing the total valuation by enormous amounts.
The Discount Rate: WACC
The appropriate discount rate for a company's free cash flows is typically the Weighted Average Cost of Capital (WACC) — a blended rate reflecting the cost of the company's debt (adjusted for the tax shield on interest) and the cost of its equity, weighted by the proportions of each in the capital structure. The cost of equity is itself estimated using models such as the Capital Asset Pricing Model (CAPM), which links required return to the volatility of a stock relative to the market (beta). Estimating WACC requires multiple assumptions, each of which introduces uncertainty.
Sensitivity to Assumptions
Photo by Horizon flights on Unsplash
A DCF model's great strength — that it forces you to make explicit assumptions about growth and risk — is also its great vulnerability. Changing the long-run growth rate from 3% to 4% in a terminal value calculation can increase the estimated value by 20–30%. Changing the discount rate from 9% to 8% can have a similarly large effect. Two analysts working from the same financial data but different assumptions can produce valuations that differ by a factor of two or more.
This sensitivity is not a reason to abandon DCF thinking. It is a reason to treat DCF outputs as a range rather than a point estimate, and to be especially careful about the assumptions driving terminal value.
DCF as a Framework, Not a Calculator
Photo by Sven Mieke on Unsplash
The most useful way to think about DCF is not as a machine that produces a precise price target, but as a framework that makes explicit what you believe about a business. When you build a DCF, you are answering: how much cash will this business generate? How fast will it grow? How risky is it? Those are the right questions. The numerical output is an estimate whose value lies in the thinking required to produce it, not in the digits themselves.
Warren Buffett has described his approach as "owner earnings" valuation — a practical variant of DCF that focuses on the cash a business owner can realistically extract each year. The underlying logic is identical to Williams' 1938 formulation.