
The Normal Distribution and Its Assumptions
Photo by Mick Haupt on Unsplash
Modern Portfolio Theory is built on the normal distribution — the symmetric bell curve familiar from statistics. In a normal distribution, outcomes close to the mean are common, and outcomes far from the mean become exponentially rarer. Under normality, a return more than three standard deviations from the mean should occur about 0.3% of the time (roughly once every 300 observations). A five-sigma event should occur roughly once every 3.5 million observations.
Standard deviation, the central risk measure in MPT, is calibrated to the normal distribution. When investors speak of a fund's 15% annual volatility, they are implicitly assuming that this number captures the distribution of returns adequately — that 15% standard deviation tells you most of what you need to know about how extreme the outcomes might be.
The problem is that real financial returns are not normally distributed, and the departures from normality are not small.
Fat Tails in Practice
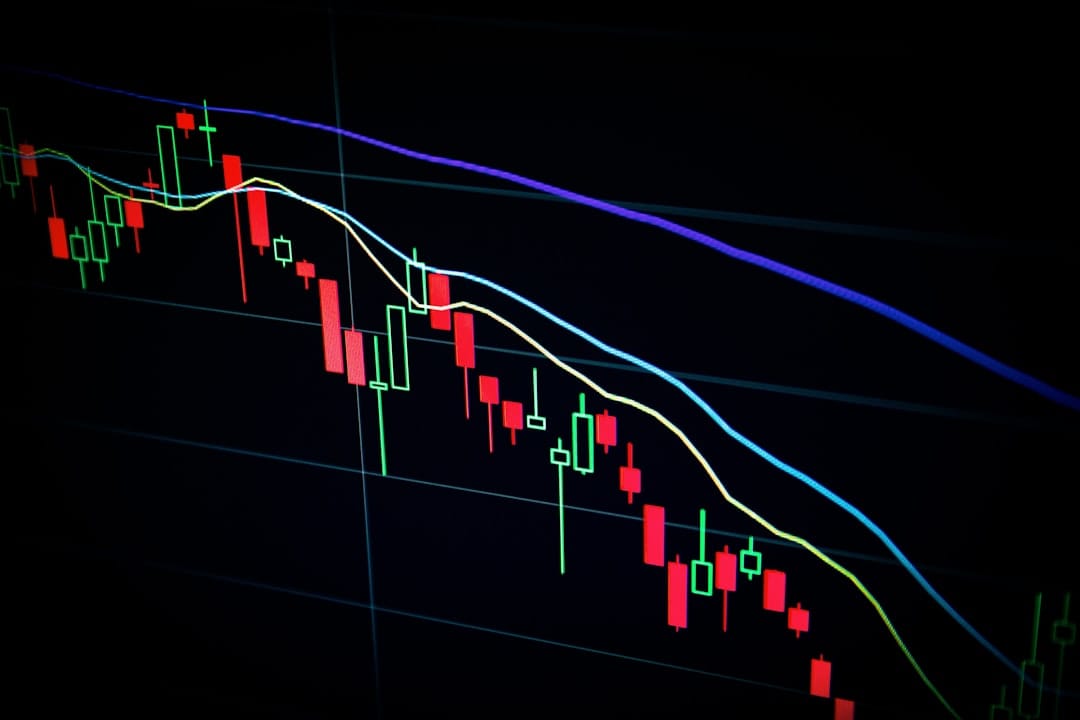
Photo by Maxim Hopman on Unsplash
Fat tails (formally: leptokurtosis) means that extreme events occur far more often than the normal distribution predicts. The tails of the actual return distribution are "fatter" than the bell curve — there is more probability mass far from the mean in both directions.
The 2008 financial crisis provided a stark demonstration. Collateralised debt obligations, mortgage-backed securities, and many equity markets experienced moves that their risk models — calibrated to the normal distribution — assigned probabilities of occurring once in tens of thousands of years. Multiple such events occurred within weeks of one another in September and October 2008. The models were not wrong about the mathematics; they were wrong about the distribution.
David Li's Gaussian copula model, used to price CDOs, assumed normally distributed default correlations. When default correlations spiked during the crisis, the model's predictions failed catastrophically. This failure played a material role in the 2008 financial crisis, making it arguably the most consequential mathematical modelling error in financial history.
Negative Skew
Photo by Sharad Bhat on Unsplash
Beyond fat tails, financial returns tend to be negatively skewed: the distribution is asymmetric, with the left tail (large losses) being longer and fatter than the right tail (large gains). Markets crash faster than they rise; investors experience more frequent small-to-moderate gains but occasional severe and rapid losses.
Negative skew is particularly dangerous because it is invisible in standard deviation. A strategy with 10% annual volatility, negative skew, and fat tails may seem comparable to a strategy with 10% annual volatility and a near-normal distribution — but the first strategy has a materially higher probability of a catastrophic loss.
Mandelbrot and Power Laws
Photo by Yuriy Vertikov on Unsplash
Benoit Mandelbrot, the mathematician celebrated for fractal geometry, argued in The (Mis)Behavior of Markets (2004, co-authored with Richard Hudson) that financial returns follow power-law distributions — also known as fat-tailed or Pareto distributions — rather than Gaussian (normal) distributions. Under power laws, extreme events are merely improbable, not astronomically improbable. The ratio between the probability of a five-sigma event and a three-sigma event is far smaller under a power law than under a Gaussian.
Mandelbrot's critique was systematic: he argued that Gaussian assumptions systematically and predictably underestimate market risk, and that the entire apparatus of MPT — efficient frontiers, CAPM, Black-Scholes option pricing — inherits this fundamental flaw.
Nassim Taleb's The Black Swan (2007) extended this critique to epistemology: not only are extreme events more probable than Gaussian models suggest, but the most impactful events are precisely those that were not contemplated in advance. The expected-value framework of MPT gives no weight to events outside the observed sample, leaving investors dangerously exposed to genuinely unprecedented outcomes.
Implications for Portfolio Construction
Photo by Precondo CA on Unsplash
The practical implications are significant. Value at Risk (VaR) calculations based on normal distributions systematically understate the probability of large losses. Stress testing against historical scenarios partially addresses this but is limited to scenarios that have already occurred. Standard portfolio optimisation, conducted in mean-variance space, gives no explicit consideration to tail risk.
Approaches that attempt to address fat tails include: using historical simulation rather than parametric VaR, incorporating Conditional Value at Risk (CVaR or Expected Shortfall) as a risk measure, and using fat-tailed distributions (like Student's t-distribution) in place of the normal distribution. None of these fully solves the problem — uncertainty about tail behaviour is irreducible — but they are meaningfully more honest about the risks involved.