
Beyond Domestic Bonds
Photo by FilterGrade on Unsplash
Most investors who hold bonds hold them primarily in their home country. The pull of the familiar — home bias — applies as strongly to fixed income as to equities. But the global bond market is vast: as of the mid-2020s, it exceeds $130 trillion in outstanding debt, spanning government bonds from over 100 countries, corporate bonds across many currencies, and supranational debt from institutions like the World Bank and European Investment Bank.
Accessing global fixed income introduces both opportunities and risks that differ substantially from domestic bond investing. Understanding these dimensions is essential for any investor considering international bond exposure.
Developed Market Government Bonds
Photo by Katie Moum on Unsplash
The core of global fixed income is the government bond markets of major developed economies: the United States (US Treasuries), Germany (Bunds), Japan (JGBs), the United Kingdom (Gilts), and France (OATs). These markets are deep, liquid, and — at least for the largest issuers — typically low credit risk.
Each market has its own yield curve, policy interest rate, and monetary framework. Investors in global fixed income are therefore not just buying interest rate exposure — they are taking implicit views on the relative monetary policies of multiple central banks. When the US Federal Reserve tightens while the Bank of Japan holds rates near zero, the interest rate differential creates both a return opportunity and a currency risk for international investors.
The Currency Dimension
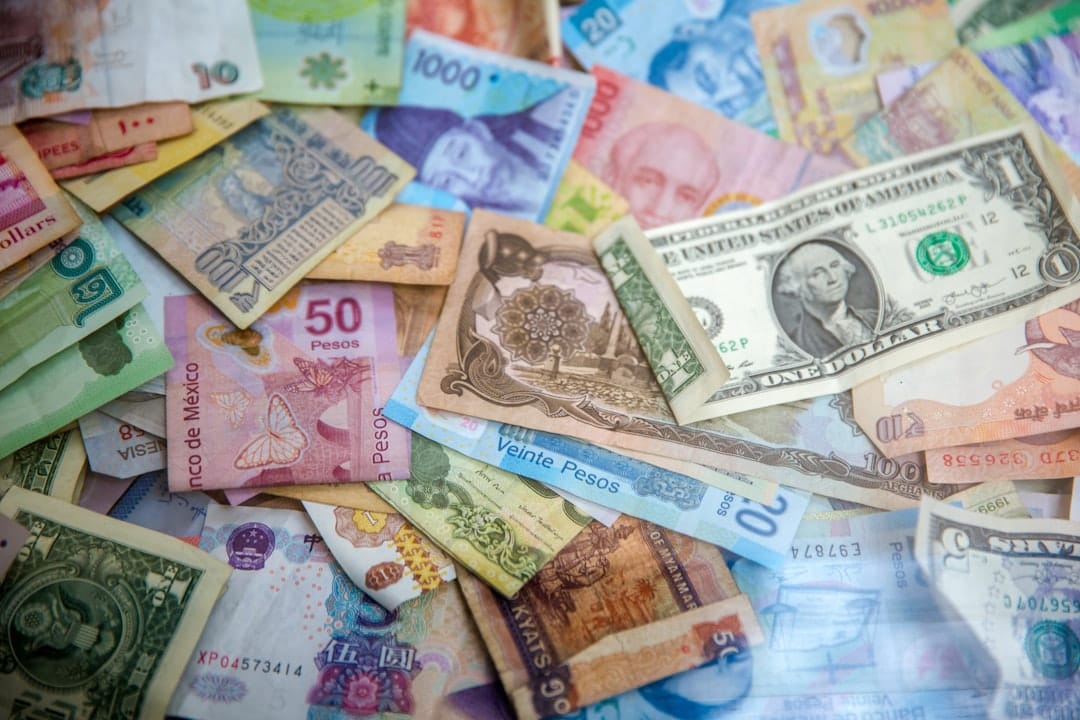
Photo by Jason Leung on Unsplash
Investing in a Japanese government bond as a US dollar investor involves two exposures: the interest rate dynamics of the Japanese bond market, and the exchange rate between the yen and the dollar. If the yen falls against the dollar, the dollar-denominated return from the Japanese bond will be reduced or eliminated, even if the bond itself performs well in yen terms.
Investors who want the diversification benefits of global bonds without full currency exposure typically hedge the currency risk — using forward contracts or swap instruments to lock in the exchange rate over the investment period. Currency-hedged global bond indices (such as the Bloomberg Global Aggregate hedged to USD) provide exposure to international interest rate dynamics while neutralising currency movements. Hedging has a cost: the forward rate premium or discount reflects the interest rate differential between currencies, meaning hedging high-yielding currencies into a low-yield base currency incurs a cost roughly equal to the yield spread.
Emerging Market Bonds
Photo by Spencer Watson on Unsplash
Emerging market (EM) bonds offer yields significantly higher than developed market equivalents, reflecting the higher risks: greater inflation volatility, less established central bank credibility, higher default probability (particularly for corporate issuers), and currency volatility.
EM bonds come in two main forms. Hard currency bonds are issued by EM governments or corporations in US dollars or euros, eliminating local currency risk for the foreign investor but retaining credit risk. Local currency bonds are issued in the country's domestic currency, exposing investors to both credit and currency risk but providing access to potentially higher real yields.
The JP Morgan EMBI (Emerging Market Bond Index) tracks hard-currency sovereign EM bonds and is the most widely followed EM fixed income benchmark. During risk-off periods, EM bond spreads over US Treasuries typically widen sharply as investors flee to safety — creating both the opportunity and the risk that characterises the asset class.
Practical Portfolio Considerations
Photo by Dmytro Yarish on Unsplash
Global fixed income adds diversification value when domestic and international interest rate cycles diverge. When the US is raising rates while Europe is easing, a globally diversified bond portfolio will experience less concentrated rate risk than one limited to a single market. In practice, however, correlations between major bond markets have risen over time as global capital markets have become more integrated.